Insurance inspections · St. Johns County
Four-Point & Wind Mitigation Inspections
Understand what your insurer is asking for. A Four-Point report documents four major home systems. A Wind Mitigation report documents construction features used in evaluating wind risk and potential insurance credits. You may need one report or both.
For homeowners in St. Johns County and St. Augustine.
Have a request from your insurance agent? Keep the requested report names and deadline handy.
Two reports, different questions
Which report do you need?
Insurance companies use these reports for different purposes. Your agent can tell you which report, form and supporting information your insurer requires for your property.
| Four-Point | Wind Mitigation | |
|---|---|---|
| Main question | What is the visible condition of the roof, electrical, plumbing, and heating and cooling systems? | What wind-resistance construction features can be verified and documented? |
| Typical use | Information for an insurer reviewing a new policy, renewal or other underwriting requirement. | Information for an insurer evaluating wind-related construction features and possible mitigation credits. |
| Focus | Four major systems, their condition, age information and relevant concerns within the requested form. | Building information, roof features, attachments, water resistance and opening protection covered by Florida’s uniform form. |
| Report | A Four-Point report with supporting photographs. | A separate Uniform Mitigation Verification Inspection Form with supporting evidence. |
Four-Point
- Main question
- What is the visible condition of the roof, electrical, plumbing, and heating and cooling systems?
- Typical use
- Information for an insurer reviewing a new policy, renewal or other underwriting requirement.
- Focus
- Four major systems, their condition, age information and relevant concerns within the requested form.
- Report
- A Four-Point report with supporting photographs.
Wind Mitigation
- Main question
- What wind-resistance construction features can be verified and documented?
- Typical use
- Information for an insurer evaluating wind-related construction features and possible mitigation credits.
- Focus
- Building information, roof features, attachments, water resistance and opening protection covered by Florida’s uniform form.
- Report
- A separate Uniform Mitigation Verification Inspection Form with supporting evidence.
Neither inspection replaces a full home inspection. Insurers set their own requirements and make their own coverage and premium decisions.
Four-Point
Four systems. A focused insurance report.
A Four-Point inspection documents the visible and accessible condition of the roof, electrical, plumbing, and heating and cooling systems. Insurers may request this information to assess the property before issuing or renewing coverage. Requirements vary by insurer and property; a Four-Point report is not required for every Florida home.
The four systems at a glance.
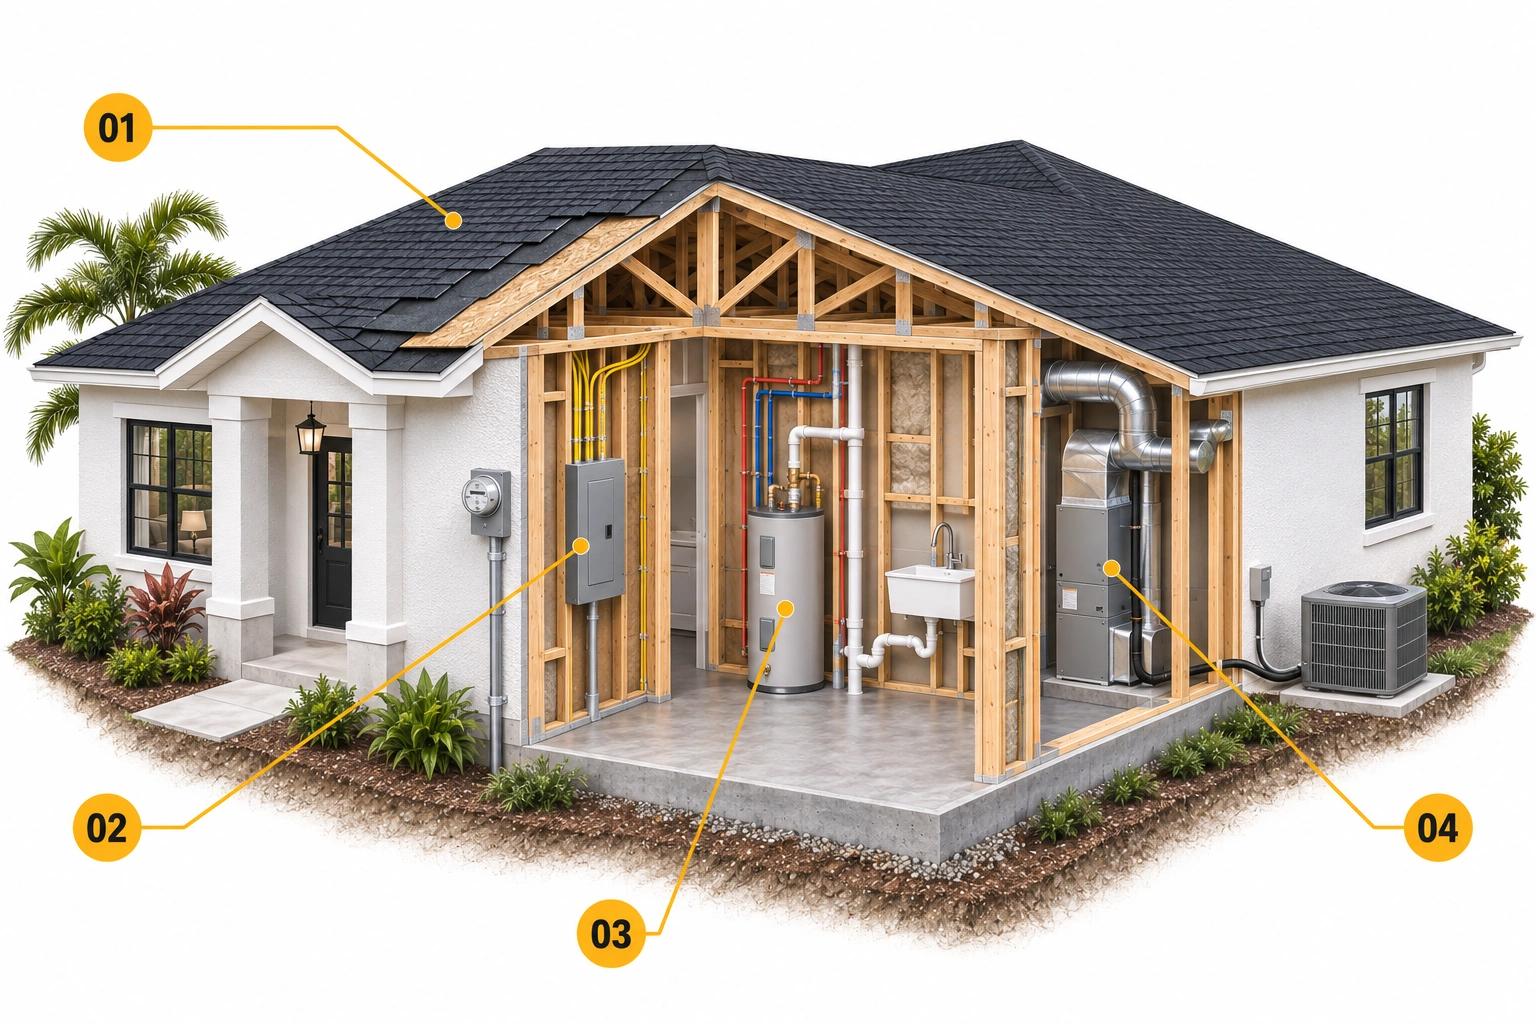
- 01
Roof
Roof covering, visible condition, available age information, and signs of leakage or deterioration within the requested scope.
- 02
Electrical
Electrical service, panels, and visible wiring, including observed conditions relevant to the insurer’s report.
- 03
Plumbing
Visible supply and drain piping, fixtures, and water-heating equipment, including observed leaks and available age information.
- 04
Heating and cooling (HVAC)
Installed heating and cooling equipment, available age information, and visible or operational conditions within the agreed scope.
Numbers identify the illustration key. They are not official form question numbers, inspection steps, findings or ratings.
Why your insurer may ask for it
An insurer may need current information about these systems before deciding whether to offer or continue coverage, request repairs or seek further evaluation. The inspection records what can be observed and documented. It does not decide whether the insurer will accept the property.
Ask about a Four-Point inspectionWind Mitigation
Document the features that matter to a wind review.
A Wind Mitigation inspection records construction features on Florida’s Uniform Mitigation Verification Inspection Form. The inspection combines visible, accessible evidence with supporting records where the form permits them. An insurer may request the report, or a homeowner may obtain one for consideration of available mitigation credits.
A closer look at wind-resistance features.
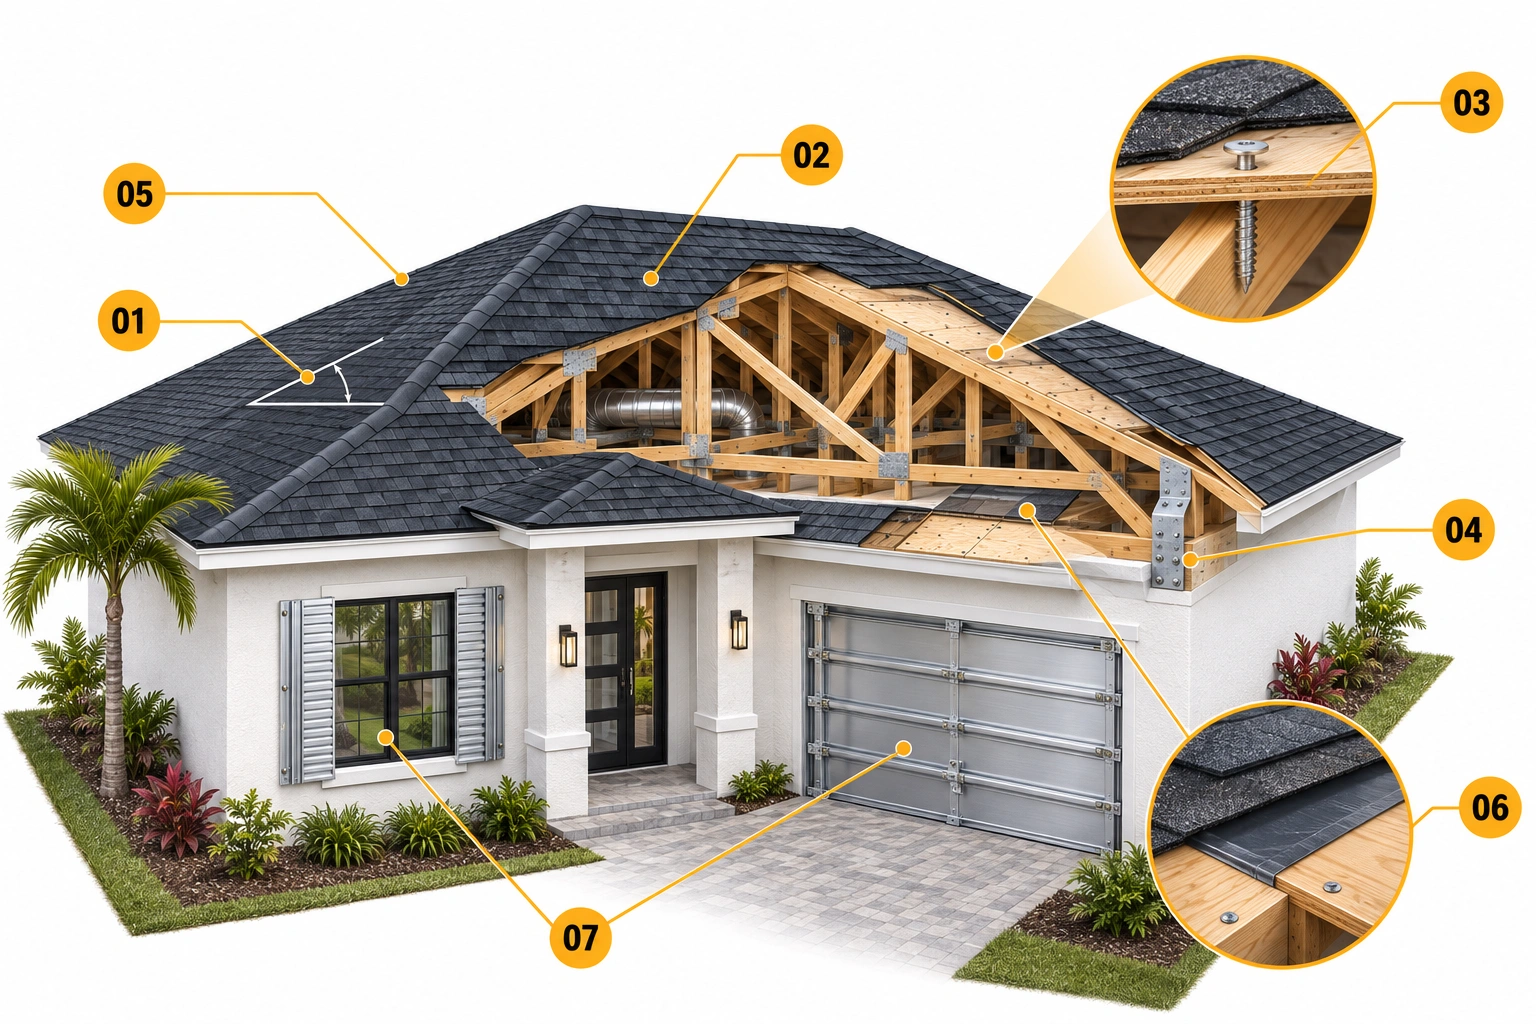
- 01
Roof slope
The roof’s pitch or angle.
- 02
Roof covering
Roofing material and relevant supporting installation or approval records.
- 03
Roof-deck attachment
How roof sheathing is fastened to the supporting framing.
- 04
Roof-to-wall attachment
Connections securing roof framing to the supporting walls.
- 05
Roof geometry
The overall roof shape, such as hip or gable. This is different from slope.
- 06
Sealed roof deck / secondary water resistance
Qualifying measures beneath the covering, supported by the applicable evidence. Ordinary underlayment does not automatically establish this feature.
- 07
Opening protection
Documented protection for applicable windows, doors, garage doors, skylights, and other openings covered by the form.
Numbers identify the illustration key. They are not official form question numbers, inspection steps, findings or ratings.
What the report considers
The current Florida form, OIR-B1-1802 Rev. 04/26, applies to inspections from April 1, 2026. Its nine questions include building-code and region information as well as the seven physical topics pictured above.
- Building information and location
- Applicable building-code information, records and the property’s wind region.
- Roof slope, shape and covering
- The roof’s slope and geometry, its covering and relevant supporting documentation.
- Roof-deck attachment
- How the roof sheathing is fastened to the framing, where it can be verified.
- Roof-to-wall attachment
- The connections between roof framing and the supporting walls, where they can be verified.
- Sealed roof deck or secondary water resistance
- Qualifying measures beneath the roof covering, where supported by the required evidence. Ordinary roof underlayment does not automatically establish this feature.
- Opening protection
- Documented protection for applicable windows, doors, garage doors, skylights and other openings covered by the form.
Why the documentation matters
Two homes that look similar from the street can have different connections, roofing details and opening protection. A photograph, product marking, permit or other accepted record may help document a feature. An earlier report or an owner’s description does not by itself establish the current result.
The report describes the evidence available at the inspection. It does not guarantee a credit, premium reduction or how the home will perform in a hurricane.
Ask about Wind MitigationTwo distinct reports
Need both? Request them together.
If your insurer needs both reports, tell us when you inquire. We can review whether both inspections can be arranged for the same visit, based on the property, access and requested scope.
You still receive two distinct reports. A Four-Point report does not replace a Wind Mitigation report, and a Wind Mitigation report does not replace a Four-Point report.
Ask about both inspectionsPreparation and access
What to have ready
A little preparation helps us understand the request and document what is available. Send the report names and deadline first; we will discuss any additional records and access arrangements with you.
For your inquiry
- The property address and type of home.
- Four-Point, Wind Mitigation, or both.
- The insurance agent’s or insurer’s request, including any named form and photo requirements.
- Your policy, renewal or closing deadline.
- Known access limitations or recent work affecting the requested inspection.
Before the visit
- Arrange permission to enter the home and access the relevant areas.
- Provide clear access to the electrical panel, water heater, heating and cooling equipment, plumbing fixtures and attic access opening where needed.
- Discuss utility status in advance. Do not energize unsafe equipment or restore a disconnected utility for the inspection yourself.
- Gather available roof permits, replacement records, product approvals, opening-protection documentation and relevant previous reports. Tell us if records are unavailable.
- Secure pets and let us know about locked areas, stored belongings or other access concerns.
You do not need to climb onto the roof, enter the attic or remove electrical covers. We will explain the access needed for the agreed inspection.
From inquiry to report
What happens next
Confirm the request.
We review the requested service, property, deadline and any insurer-specific requirements with you.
Agree on the visit.
Scope, fee, access and timing are confirmed before the inspection is arranged.
Document the evidence.
The inspection records visible and accessible conditions and the information supported by the applicable form. Limitations are recorded.
Receive the report.
You receive the selected report or reports and supporting photographs for your insurance review. Your insurer or agent may ask for clarification, further evidence or repairs.
A follow-up visit or additional work is discussed separately if needed. Report delivery timing is confirmed for your request.
Focused inspections
Clear scope. Clear limits.
These are focused insurance inspections. They do not evaluate every part of the property or rule out hidden defects. A cutaway illustration shows where systems and features are located; it does not mean concealed construction can be inspected.
The reports do not guarantee insurance acceptance, continued coverage, a premium reduction or hurricane protection. They are not engineering certifications or promises that a home is defect-free. If you are buying a home and need a broader condition review, see our Buyer Home Inspection or Condo Inspection services.
Witness Point does not perform repairs on homes it inspects.
Questions
Questions about Four-Point and Wind Mitigation
What is the difference between Four-Point and Wind Mitigation inspections?
A Four-Point report documents the condition of the roof, electrical, plumbing, and heating and cooling systems for underwriting review. A Wind Mitigation report documents construction features for an insurer’s consideration of mitigation credits. Your agent can tell you which report or reports your insurer requests. They are separate reports, neither replaces a full home inspection, and neither guarantees coverage or a premium reduction.
Do I need a Four-Point inspection, Wind Mitigation, or both?
Ask your insurance agent which reports your insurer requires. The answer depends on the insurer, property and purpose of the request. If you have a written request, share the report names and deadline with us so we can discuss the correct scope.
Why is my insurance company asking for a Four-Point report?
It may need current information about the roof, electrical, plumbing, and heating and cooling systems for underwriting. The report provides information for that review. It is not an approval of the property for insurance.
Does Wind Mitigation lower my insurance premium?
A documented feature may qualify for a mitigation credit under your insurer’s rules. The insurer determines whether a credit applies and how it affects the premium. An inspection does not guarantee savings.
Can both inspections be completed during one visit?
Request both when you contact us. We will review the property, access and requested scope before confirming whether they can be arranged together. The reports remain separate.
Can either report replace a buyer’s home inspection?
No. These reports address specific insurance questions. A buyer’s home inspection has a broader agreed scope and helps you understand more of the property’s visible and accessible condition.
What if the attic is inaccessible or a feature cannot be verified?
We document the limitation and report only what the available evidence supports under the form. Access restrictions or missing documentation can affect the completed report. Additional evidence or a return visit may be needed; we will discuss that with you.
Can you use my old report, permits or roofing paperwork?
Please have them available. They may help identify relevant information, but they do not automatically establish the property’s current condition or satisfy every evidence requirement. We review them within the applicable form and inspection scope.
Will my insurer accept the report?
Acceptance belongs to the insurer. Tell us the insurer’s requested form and supporting requirements before the visit so we can confirm whether the request fits our service. The insurer may still ask for further information or work.
Do you make repairs if a problem is found?
No. Witness Point keeps inspection and repair work separate and does not perform repairs on homes it inspects.
How much does it cost, and when will I receive the report?
Contact us with the property details, report choice and deadline. We will confirm the scope, fee and delivery timing before you commit to the inspection. Requesting both reports does not automatically establish a package price or discount.
Start with the report you need
Let’s review your insurance inspection request.
Choose Four-Point, Wind Mitigation, or both. Tell us the property address and any insurance deadline. We will confirm service availability, scope and timing before arranging a visit.
Not sure which report was requested? Contact Witness Point and we will help you identify the question to ask your agent.
Sending an inquiry does not reserve an appointment. An appointment is confirmed only after we discuss the property, service, access and timing with you.